The Oklahoma State Farm settlement may create a review path for certain homeowners whose wind or hail roof claims were denied, underpaid, or closed below the deductible between 2021 and 2025. It is not automatic, and opting in can require a careful decision if you have an active lawsuit or lawyer.
Who may receive a State Farm notice in Oklahoma?
The settlement process is aimed at some Oklahoma State Farm policyholders with wind or hail roof claims from January 1, 2021, through December 31, 2025. A prior denial is not necessarily the final answer, but eligibility and payment still depend on the review process.
The claim history described for review includes homeowners whose roof claim was:
- Denied outright.
- Paid at an amount they believe was substantially too low.
- Closed because the damage was said to fall below the deductible.
State Farm was expected to send a notice approved by the Oklahoma Insurance Department by December 31, 2026. Do not assume every homeowner with storm damage will receive one. Keep your policy and claim records accessible so you can compare any notice with your own claim number, property address, and loss information.
Verify the notice before sharing claim records
An official letter is the starting point, not a reason to sign a new roofing contract. The Oklahoma Insurance Department warned that the settlement could attract scams and said official communications would come from State Farm or the department.
That matters because a contractor, door knocker, or caller may know that homeowners are receiving settlement-related mail and use it as a sales opening. They cannot decide your eligibility or promise a settlement payment. If a message seems questionable, contact State Farm or the Oklahoma Insurance Department through contact information you locate independently, rather than using a phone number or link supplied by an unsolicited caller.
Be especially cautious if someone claims they can reopen your claim only if you hire them immediately. The settlement review is not a reason to rush into a roof replacement agreement.
Build the file for an independent claim review
The administrator may consider new proof as well as the old claim file. Your strongest move is to organize records that show what happened, what State Farm decided, and what repairs or costs followed.
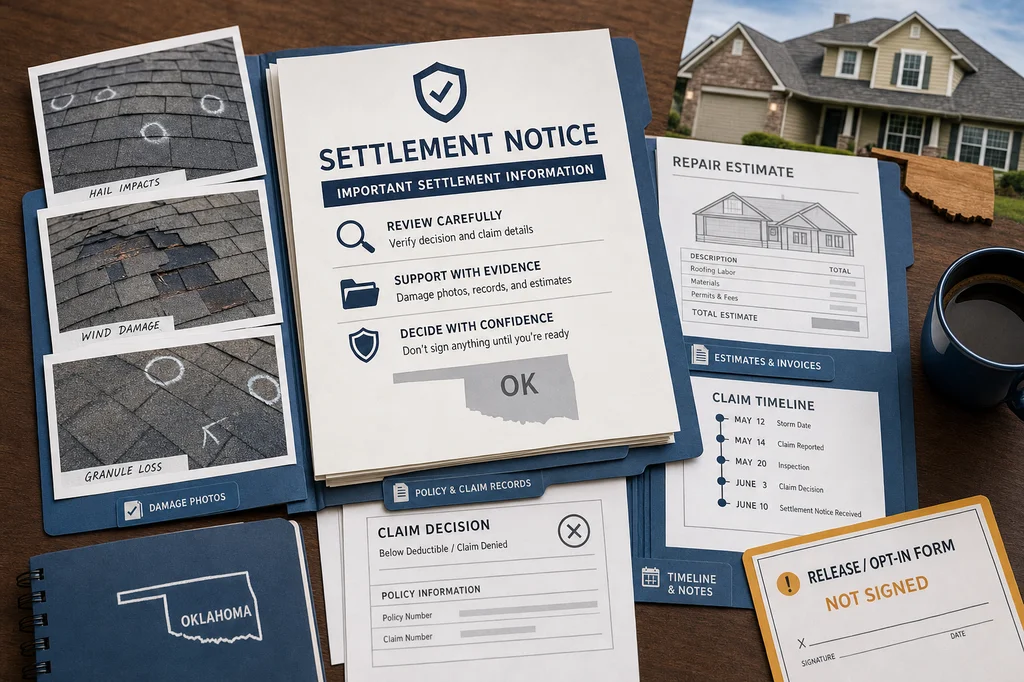
Gather copies rather than relying on a contractor or insurer to reconstruct the history later:
- The original claim decision. Save denial letters, below-deductible letters, payment explanations, estimates, and correspondence.
- Damage documentation. Collect dated photos, videos, and any reports created near the time of the wind or hail event.
- Repair records. Keep invoices, receipts, paid bills, financing documents, and records of temporary repairs.
- Prior contractor materials. Preserve written estimates, scope documents, and reports that describe the claimed roof damage.
- Your timeline. Write down the storm date, inspection dates, claim number, adjuster visits, payments, and major communications while you can still locate the records.
This is not a chance to recreate evidence that never existed. It is a chance to submit relevant records that may not have been fully considered in the original decision. A qualified roofing professional can help document the roof’s present condition and identify repair records, but should not promise what an insurance review will pay.
Why the settlement does not guarantee a payment
A review can produce payment under the policy if the administrator concludes the claim should have been paid, but payment is not guaranteed. The settlement calls for an independent third-party claims administrator rather than State Farm to review participating claims.
The Oklahoma Insurance Department identified substantial violations of the state’s unfair claim settlement practices law during its examination. News reports described one sample in which 27 of 58 roofs reviewed by the state had damage but received no payment. That sample is a reason to take an old decision seriously; it is not proof that every denied claim was mishandled.
The settlement includes a minimum $35 million restitution fund, with the department stating that more money could be added if approved claims require it. State Farm has disputed the examination’s findings and characterizations and has not admitted wrongdoing. For a homeowner, the practical point is simple: submit a complete file, but do not budget for money until the review reaches a decision.
Consider the lawsuit-release tradeoff before opting in
A settlement payment may require you to release litigation-related claims, which can be a major decision for homeowners who have already sued State Farm. Oklahoma Attorney General Gentner Drummond said participating homeowners must sign away bad-faith claims and that people with pending lawsuits must drop them to collect.
The reported settlement structure may limit recovery through this process to amounts State Farm already owed under the policy. Whether that tradeoff makes sense depends on your own policy, claim record, contract, and legal case. Do not treat a settlement notice as a substitute for advice from the lawyer handling your lawsuit.
If you already have an attorney, send that attorney the notice and proposed release before opting in or signing anything. If you do not have a lawsuit, read every form closely and consider legal advice if you do not understand what rights the release affects. Insurance coverage and claim-related legal rights can vary by policy and circumstance.
Use roof documentation without turning the settlement into a sales pitch
You may need current roofing documentation, particularly if old photos, invoices, or reports are incomplete. The goal is a clear record for the claim review, not a rushed agreement with the first company that contacts you after a notice arrives.
Before hiring someone to inspect or document roof conditions, request a written description of what they will provide. It should distinguish current observed conditions from older claim records and avoid guaranteeing insurance approval or a full replacement. Keep control of your claim documents and read any authorization before signing.
For roof documentation or repairs, Directorii lists verified contractors.
What to do after a settlement letter arrives
Act methodically once you receive a notice. The reported process gives homeowners 180 days after the initial notice to opt in, but rely on the deadline printed in your official notice and preserve proof of submission.
- Confirm that the notice is authentic through State Farm or the Oklahoma Insurance Department.
- Match the notice to your old claim records and property address.
- Make a complete copy of the notice, forms, release language, and every item you submit.
- Organize your denial letter, estimates, photos, invoices, and repair records before sending them.
- Have an attorney review the documents first if you have a pending lawsuit or legal representation.
- Keep proof of when and how you opted in or submitted evidence.
This process may offer a fresh review of an old roof claim. It does not remove the need to verify the notice, document the loss carefully, and understand what you may be giving up before accepting payment.
Source: YouTube
FAQ
Who may be eligible for the Oklahoma State Farm roof claim settlement?
Some Oklahoma State Farm homeowners with wind or hail roof claims from January 1, 2021, through December 31, 2025, may be considered. The described group includes certain denied claims, partial payments, and claims closed below the deductible. Eligibility is not automatic and depends on the official notice and review process.
Do I automatically get paid through the Oklahoma State Farm settlement?
No, a payment is not guaranteed through the settlement process. An independent third-party claims administrator may review the prior claim file along with new evidence you submit. If the administrator concludes the claim should have been paid, State Farm may pay according to the terms of the policy.
What documents should I save for a State Farm roof claim review?
Save the original denial or payment decision, claim correspondence, photos, videos, contractor reports, estimates, invoices, receipts, and records of repairs. A dated timeline of the storm, claim filing, inspections, and communications can also help organize the file. Submit copies and retain a complete set for yourself.
Should I opt in if I already sued State Farm over my roof claim?
Talk with the attorney handling your case before opting in or signing a release. The reported settlement terms may require participants to release bad-faith claims, and homeowners with pending lawsuits may need to drop those suits to collect. The right choice depends on your legal case, policy, and proposed release language.
How can I tell whether a State Farm settlement notice is real?
Verify the notice directly with State Farm or the Oklahoma Insurance Department using contact information you find independently. Official settlement communications were described as coming from State Farm or the department. Do not rely on a door knocker, unsolicited caller, or contractor who says you must hire them to participate.